Business Loan vs Mudra Loan: Which Funding Option Fits Your Expansion Needs?
Updated On: 22 September, 2026 01:33 PM IST | Mumbai | Buzz
Compare Mudra loans and regular business loans on eligibility, loan amount, interest rates, tenure and repayment to choose funding for business expansion.


Mudra loan
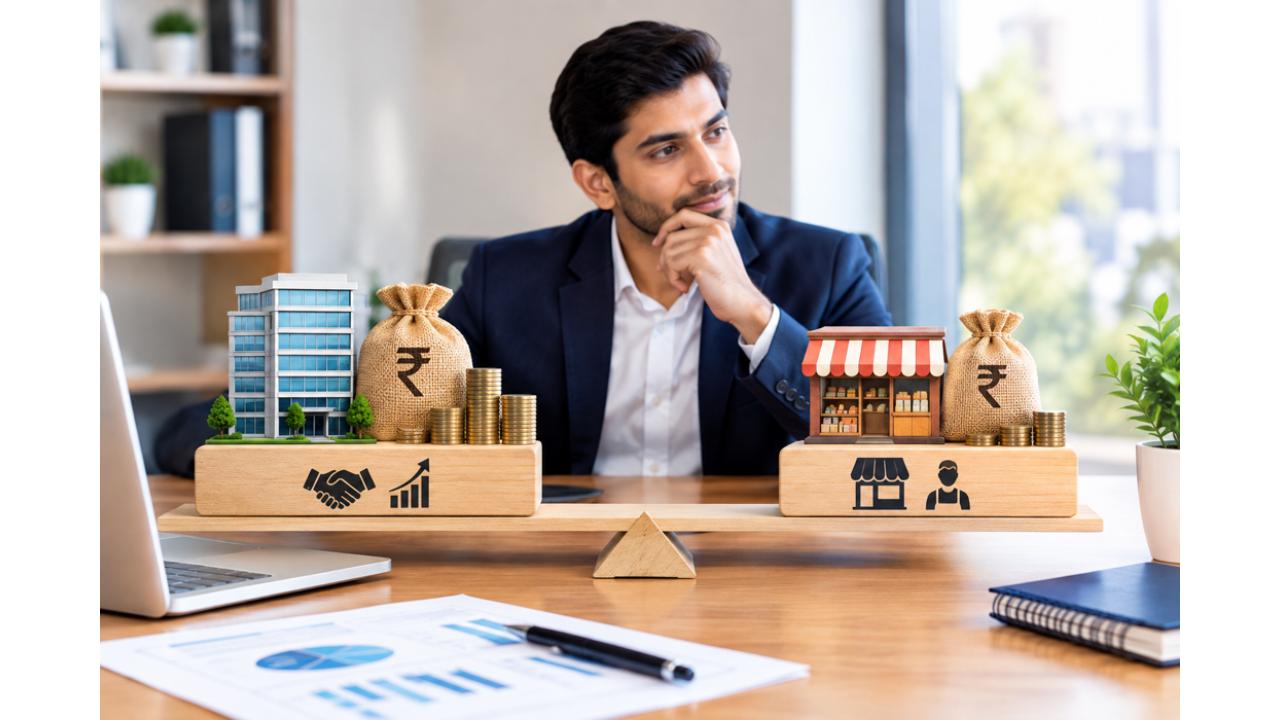
Both Mudra loans and regular Business Loans can support expansion, but they work differently. Understanding the funding limit, eligibility, pricing, and repayment structure can help you choose the more relevant route.
A business preparing to open another outlet, add machinery, increase inventory, or expand capacity often reaches the same financing question: should it explore a Mudra loan under the Pradhan Mantri Mudra Yojana (PMMY), or consider a regular unsecured Business Loan from a bank or NBFC? The answer is rarely determined by loan size alone. A Mudra loan operates within a government-backed framework designed to improve access to institutional credit for eligible micro enterprises. A regular business loan is offered directly by the lender under its own credit, pricing, and repayment framework.
Other Articles
ADVERTISEMENT
Mid-Day Fast
ADVERTISEMENT